

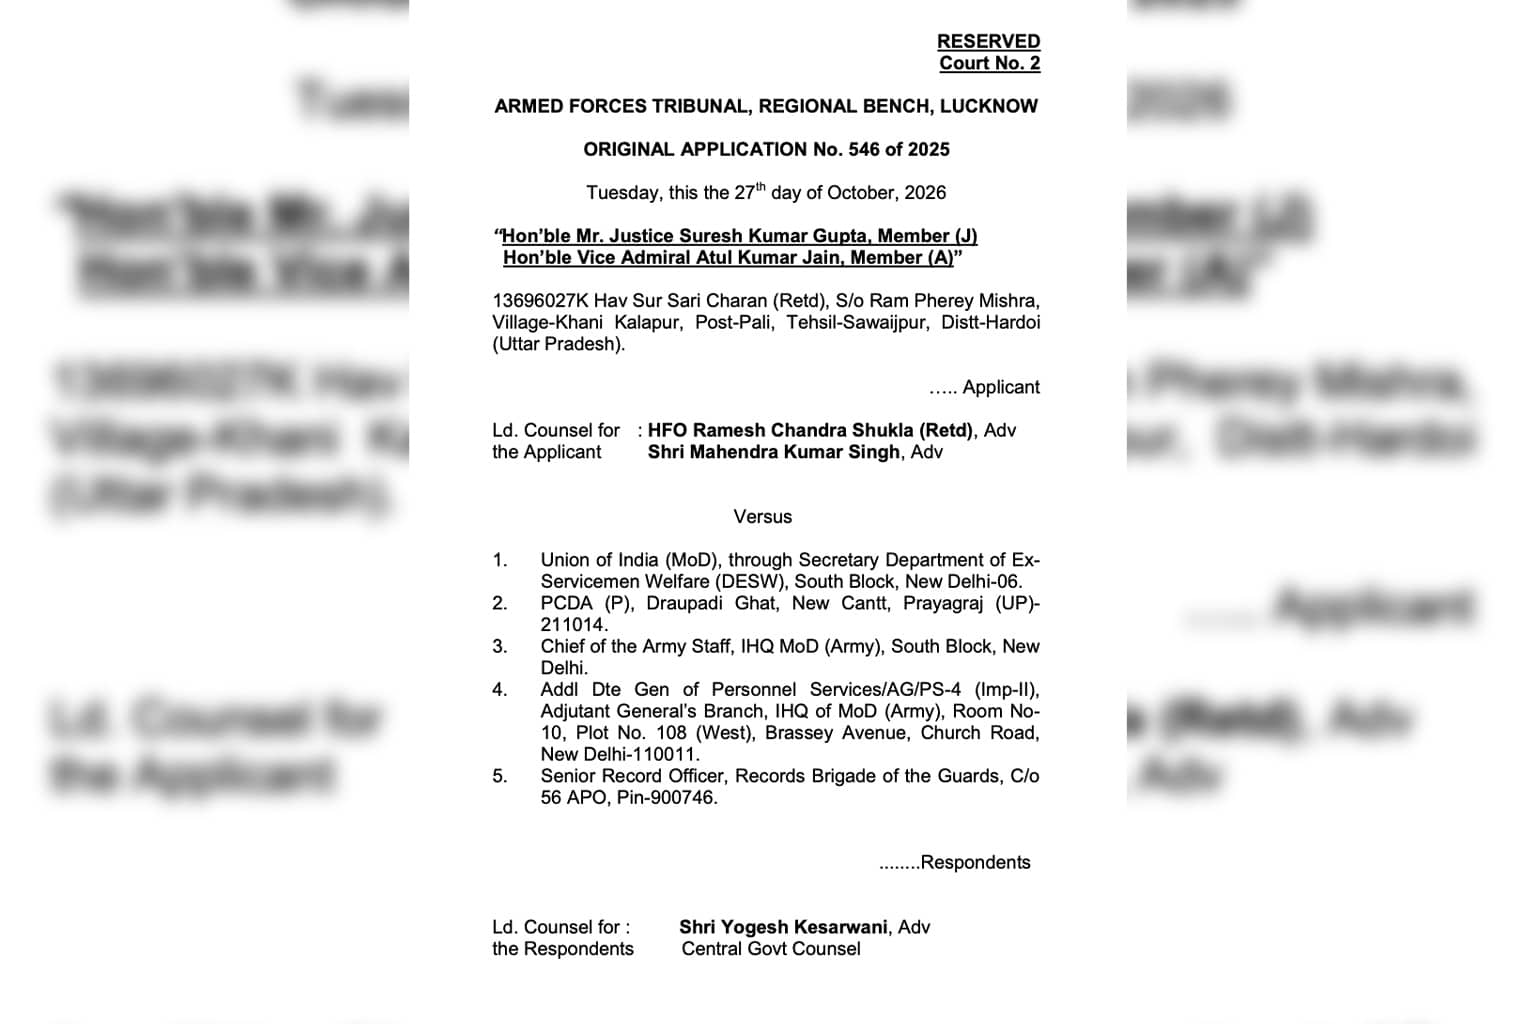
Download the Court Jugment
The Armed Forces Tribunal (AFT), Lucknow Bench, has ordered 6% annual interest and ₹25,000 in compensatory costs in a case involving wrongful pension deductions from a retired Indian Army Havildar.
In its judgment dated 27 October 2026, the Tribunal found that pension authorities continued recovering money even after an incorrectly credited commuted pension amount of ₹12,95,325 had already been returned.
The case is important for defence pensioners because it highlights the consequences of repeated pension deductions and the importance of maintaining proper payment and recovery records.

The judgment was delivered by Justice Suresh Kumar Gupta, Member (Judicial), and Vice Admiral Atul Kumar Jain, Member (Administrative).
Why was ₹12.95 lakh recovered from the Veteran?
Havildar Sur Sari Charan joined the Indian Army on 23 August 1995 and was invalided out of service on 31 May 2016. His pension started on 1 June 2016.
On 13 June 2024, an additional ₹12,95,325 was mistakenly credited to his bank account as the commuted value of pension.
However, this commutation amount had already been paid earlier.
The veteran himself informed the authorities about the incorrect payment through an email dated 16 June 2024.
Following this intimation, the full incorrectly credited amount was recovered from his bank account on 31 July 2024.
Despite this, further deductions began from his regular pension in November 2024 towards the same excess payment.
The veteran raised the issue with the concerned authorities, but the dispute remained unresolved and eventually reached the Armed Forces Tribunal.

The Tribunal specifically recognised that the veteran had honestly reported the incorrect payment.
What Did the Retired Havildar Demand?
The applicant approached the Tribunal seeking relief against the additional pension deductions.
He requested:

During the hearing, the applicant’s lawyer informed the Tribunal that the additional amount deducted from his pension had been refunded.
The remaining dispute mainly concerned interest and compensation.
What did the Armed Forces Tribunal decide?
After examining the records, the Tribunal concluded that the original incorrect payment of ₹12,95,325 had already been recovered on 31 July 2024.
Therefore, the additional deductions subsequently made from the veteran’s pension justified financial relief.
The Tribunal issued the following directions:

The Tribunal also referred to the Supreme Court judgment in Ramrameshwari Devi and Others v. Nirmala Devi and Others, (2011) 8 SCC 249, while awarding compensation for unnecessary litigation.
Importantly, the ₹25,000 was awarded because the veteran had been unnecessarily forced into litigation.
The Tribunal partly allowed the application.
Does this judgment apply to all defence pensioners?
This judgment concerns an individual pension dispute. It does not automatically grant interest or compensation to every defence pensioner.
However, it highlights an important issue: when an incorrect pension payment has already been recovered, further deductions towards that same payment may be challenged.
Defence pensioners facing similar problems should preserve their pension records and verify whether any recovery has already been completed.
Useful documents include pension payment statements, bank statements, PPO details, SPARSH records, recovery orders and previous grievance correspondence.
These records may help establish whether a deduction is correct or requires review.
What should pensioners do if their pension is wrongly deducted?
A pensioner who notices an unexplained deduction should first compare the pension payment statement with the bank account records.
If the deduction appears incorrect, the pensioner should raise the issue with the concerned pension authority through the applicable official grievance channel.
For defence pension matters, supporting records and the relevant SPARSH or pension-authority correspondence should be retained.
If the matter remains unresolved, the pensioner may seek appropriate legal advice regarding available remedies.
The AFT judgment does not establish that every disputed pension deduction is illegal. The facts and documents of each case remain important.
Conclusion
The AFT Lucknow judgment dated 27 October 2026 provides relief to a retired Army Havildar who faced additional pension deductions after an incorrect commutation payment had already been recovered.
The Tribunal directed payment of 6% annual interest on the subsequent excess recoveries and ₹25,000 in compensatory costs.
The case underlines the importance of accurate pension records, timely correction of wrongful deductions and accountability when a pensioner is forced into unnecessary litigation.
Armed Forces Tribunal, Regional Bench, Lucknow
Case: Hav Sur Sari Charan (Retd) vs Union of India & Others
Original Application: O.A. No. 546 of 2025
Judgment date: 27 October 2026
Coram: Justice Suresh Kumar Gupta, Member (J), and Vice Admiral Atul Kumar Jain, Member (A)
Official AFT website: https://aftdelhi.nic.in/
Document: Original seven-page judgment supplied for this report.
Editorial clarification: The ₹12,95,325 represents the original incorrect commutation payment, not the total of later wrongful pension deductions. The judgment does not specify the complete amount of those subsequent deductions. The 6% interest and ₹25,000 award are case-specific judicial directions, not a new pension benefit for all veterans.


Leave a Reply